Every time a customer opens an account, applies for credit, or proves their age online, a business is making a judgment call: is this person who they claim to be? Get that wrong at scale, and the costs show up fast — regulatory penalties, chargebacks, and a reputation hit that’s far harder to repair than the fraud itself. Document verification is the mechanism businesses rely on to answer that question reliably, and the threat landscape around it has shifted meaningfully in the past few years.
Why Identity Verification Is a Business Problem, Not Just a Compliance Checkbox
Financial institutions, airlines, healthcare providers, and a growing list of online platforms verify identity for two overlapping reasons: regulatory obligation and fraud prevention. Banks and fintechs must satisfy Know Your Customer (KYC) and Anti-Money Laundering (AML) requirements set by bodies like the Financial Action Task Force (FATF) internationally and FinCEN in the U.S. (the successor framework to older FINTRAC-style guidance referenced in older articles on this topic). But even businesses with no formal regulatory mandate — online marketplaces, age-gated platforms, gig-economy apps — verify identity because the cost of not doing so has grown sharply.
The scale of the problem, according to the FTC’s most recent full-year data (2025): total fraud losses in the U.S. reached more than $15.8 billion, up roughly 24% from $12.78 billion the year before, across over 3 million fraud reports. Identity theft specifically accounted for over 1.3 million reports, with credit card fraud the single largest category. These aren’t abstract numbers — each one represents a verification failure somewhere in a business’s onboarding or transaction flow.
The New Threat: AI-Generated and Deepfake Documents
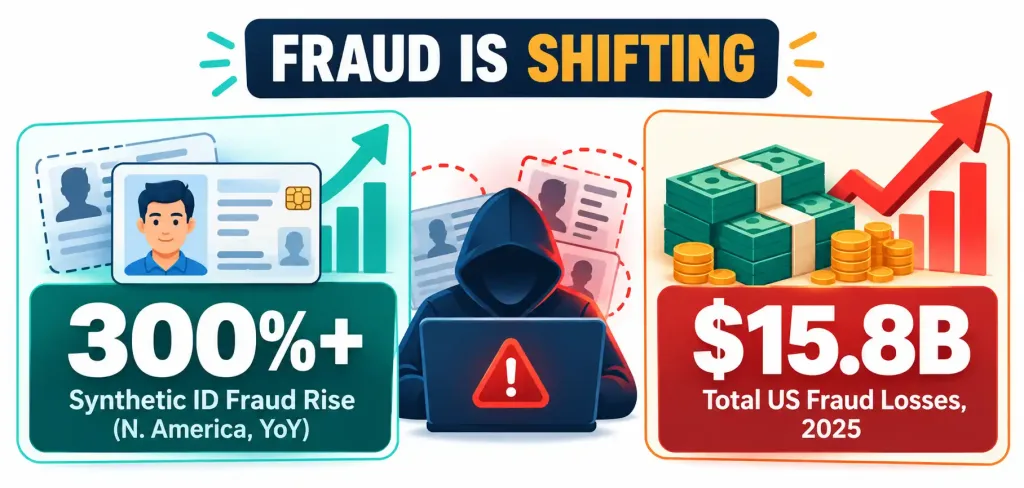
This is the part that’s changed the most since document verification first became a standard B2C practice. Fraud involving synthetic identity documents — IDs assembled from a mix of real and fabricated information, or generated outright by AI — rose over 300% year-over-year in North America during early 2025, according to identity-verification platform data. Deepfake-based fraud attempts, where AI-generated faces or voices are used to defeat biometric or facial-matching checks, have grown even faster in several markets, with healthtech and fintech reported as particularly high-risk sectors given the sensitivity and value of the data they handle.
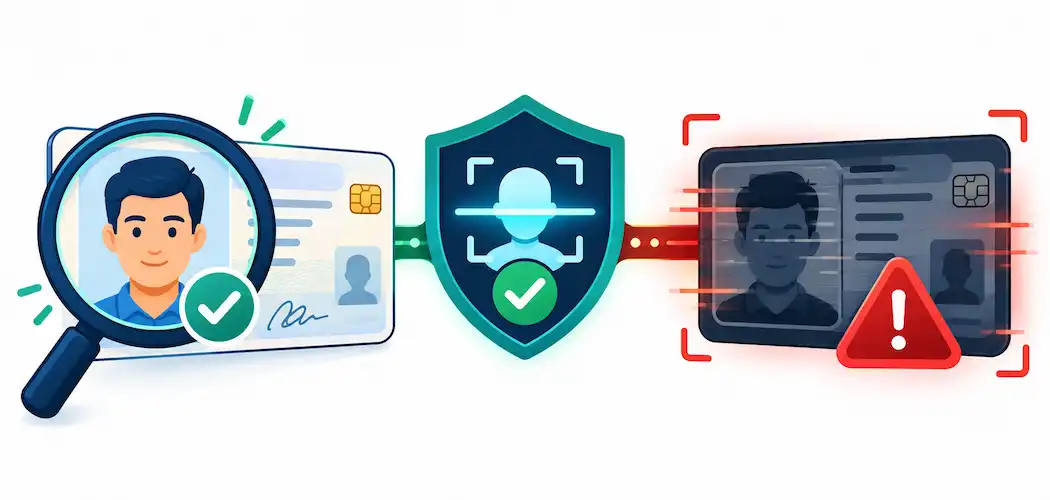
The practical implication: a verification process built only around checking whether a document looks legitimate is no longer sufficient. Modern generative AI tools can produce passport and ID images realistic enough to pass a basic visual review. This is why liveness detection — confirming that the person submitting a selfie or video is a real, present human rather than a photo, recording, or AI-generated image — has become a standard complementary layer to document checks, not an optional add-on.
What Businesses Are Actually Checking For
Three broad categories of document fraud matter here, and they require different detection approaches:
- Altered genuine documents — a real ID with modified fields (a changed birth date, swapped photo, or altered expiry date).
- Entirely fabricated documents — fake IDs built from scratch, increasingly assisted by generative AI tools that can mimic security features, fonts, and layouts convincingly.
- Genuine documents used by the wrong person — a real, unaltered ID presented by someone who isn’t its rightful owner, which document-only checks can’t catch and which is exactly why liveness and facial-matching layers exist.
How Document Verification Actually Works
A typical automated verification flow looks like this:
- Capture. The customer photographs or uploads a government-issued ID in real time (rather than uploading a pre-existing file, which is easier to manipulate or reuse).
- Extraction. Optical character recognition (OCR) pulls the data fields — name, document number, expiry date, issuing authority — directly from the image.
- Cross-verification. The extracted data is checked for internal consistency (does the document number format match the issuing country’s pattern, is the expiry date logically after the issue date) and, where available, cross-referenced against issuing-authority databases or watchlists.
- Biometric matching (increasingly standard). A live selfie or short video is compared against the document photo, with liveness checks to rule out a static photo or deepfake being used to spoof the match.
- Decisioning. Results are returned via API in seconds for straightforward cases, with ambiguous or flagged cases routed to human review.
The Real Compliance Requirements Behind “KYC”
KYC isn’t a single checkbox — in practice it typically involves Customer Due Diligence (CDD), which requires verifying identity and understanding the nature of the customer relationship, and in higher-risk cases, Enhanced Due Diligence (EDD), which goes further — checking source of funds, politically-exposed-person (PEP) status, and ongoing transaction monitoring rather than a one-time check at onboarding. Regulatory frameworks (FATF recommendations internationally, FinCEN rules in the U.S., and equivalent regimes elsewhere) generally require businesses to document how they verified a customer, not just that they did — which is why automated verification platforms that log and timestamp each verification step have become standard rather than optional infrastructure for regulated businesses.
Beyond Fraud Prevention: Age Verification and Access Control
Document verification combined with facial matching has a secondary but increasingly important use: keeping minors off age-restricted platforms and services. This has become a sharper regulatory focus in several jurisdictions recently, with some requiring verifiable age-assurance measures rather than a simple self-reported birthdate checkbox — a shift worth watching if your business operates in an age-gated category.
Choosing a Verification Approach
Businesses generally have three options: build verification in-house (resource-intensive and rarely worth it outside large financial institutions), integrate a third-party identity-verification platform via API (the most common approach — providers in this space include Jumio, Onfido, Persona, Trulioo, and several others, each with different document-coverage and liveness-detection strengths worth comparing directly), or rely on manual review alone (slow, inconsistent, and increasingly unable to catch AI-generated fraud without specialized tooling). Whichever route a business takes, the core requirement hasn’t changed: verification needs to be fast enough not to hurt conversion, accurate enough to catch both document fraud and the account-takeover attempts automated checks alone can miss, and well-documented enough to satisfy regulators if asked.
The Bottom Line
Document verification remains foundational to B2C trust, but the bar has risen considerably since this became standard practice. A document-only check that simply confirms an ID “looks real” is no longer adequate against AI-generated fakes and deepfake-assisted fraud — liveness detection and biometric matching have moved from nice-to-have to necessary. Businesses evaluating their verification setup should be asking not just “do we verify documents” but “can our current process actually catch an AI-generated fake,” since that’s increasingly the more relevant question.
Frequently Asked Questions
What’s the difference between KYC and document verification?
Document verification is one component of KYC. KYC (Know Your Customer) is the broader regulatory and risk-management framework, which includes document verification but also covers ongoing due diligence, risk assessment, and transaction monitoring depending on the customer’s risk profile.
Can document verification alone stop deepfake fraud?
No — this is one of the most important recent shifts in this space. Document-only verification can’t reliably catch an AI-generated document or a deepfake used to spoof a facial match. Liveness detection and biometric verification, used alongside document checks, are now necessary to address this specific threat.
Is document verification only required for financial services?
No. While KYC/AML obligations are strongest in regulated financial services, identity verification is now widely used across e-commerce, healthcare, gig-economy platforms, and age-restricted services, largely because the cost of fraud and account takeover has grown across all of these sectors, not just regulated ones.
How fast is automated document verification?
Straightforward cases are typically processed in seconds through an API-based verification flow. Cases flagged as ambiguous or high-risk are usually routed to human review, which takes longer but catches edge cases automated systems may miss.