The UK’s departure from the EU didn’t just change trade rules — it reshaped how financial firms operate, where they’re based, and who regulates them. Years on, the picture is clearer than it was in the immediate aftermath, and some of the early predictions (and some of the early panic) haven’t held up the way initial headlines suggested. Here’s an accurate account of what actually changed, backed by real sourced data rather than the unattributed figures that circulated in earlier coverage of this topic.
Getting the Timeline Right
A quick correction worth making upfront: the UK formally left the EU on January 31, 2020, but the Brexit transition period — during which EU financial rules still applied in full — didn’t actually end until December 31, 2020. The regulatory changes discussed here took effect from that later date, not the earlier exit date.
The Real Scale of the Shift: What the Data Actually Shows
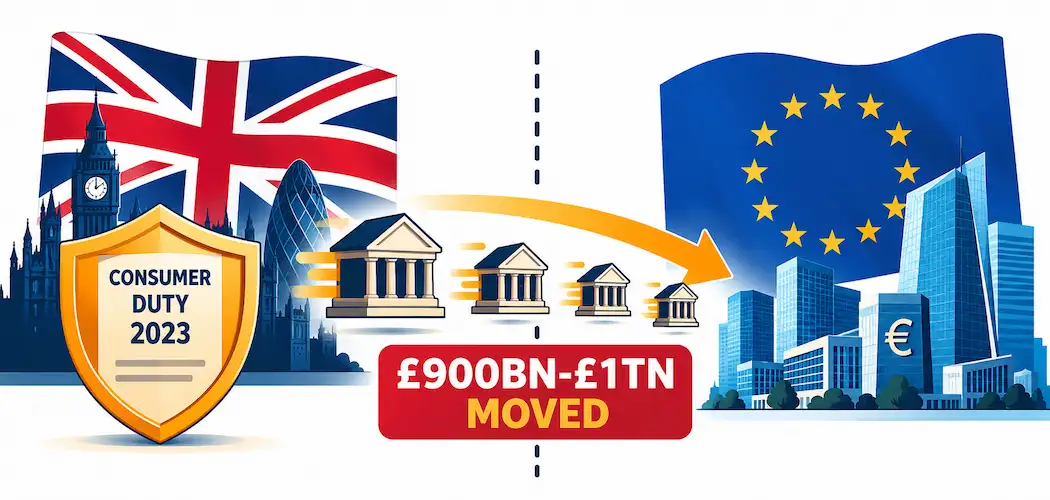
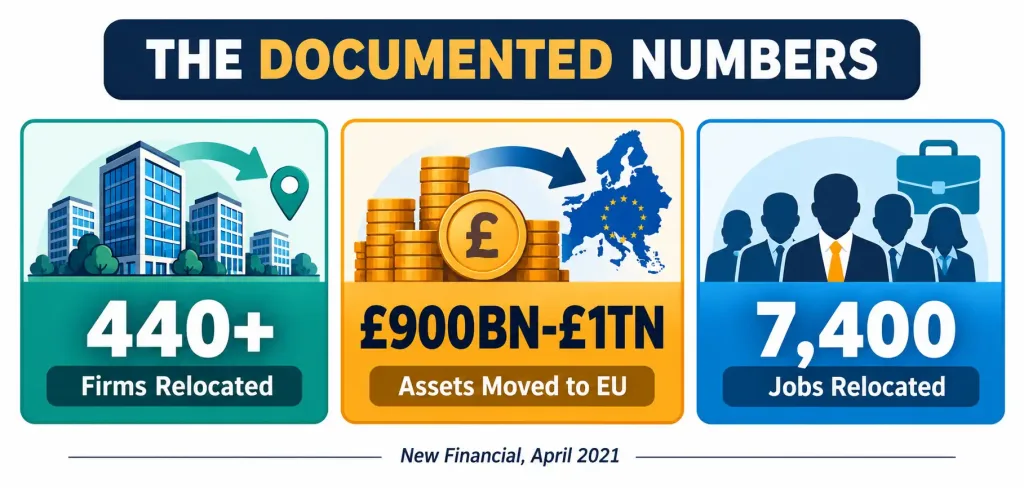
The most credible figures on post-Brexit financial relocation come from New Financial, a London-based think tank that has tracked this closely. Its April 2021 report found that over 440 financial firms had moved at least part of their business, staff, or assets out of the UK since the Brexit referendum, with roughly £900 billion to £1 trillion in assets relocated to the EU and an estimated 7,400 jobs moved alongside them — largely to Dublin, Paris, Frankfurt, Luxembourg, and Amsterdam.
Separately, in February 2021, Amsterdam briefly overtook London as Europe’s largest share-trading hub by volume, a notable symbolic moment at the time. It’s worth being honest about the fuller picture, though: this was a specific, headline-grabbing moment in early 2021 rather than a permanent reordering — London has remained a major global financial center in the years since, and the relative standing of European trading hubs has continued to shift. Treat any single month’s trading-volume snapshot as a data point, not a verdict on London’s long-term position.
The Regulatory Framework That Replaced EU Rules
The Temporary Permissions Regime (TPR) allowed non-UK (primarily EU) firms that had been “passporting” financial services into the UK to continue operating for a transitional period while seeking full UK authorization from the Financial Conduct Authority (FCA).
The Financial Services Contracts Regime (FSCR) served a narrower purpose: it let firms that didn’t enter the TPR wind down existing UK contracts in an orderly way rather than being forced to exit immediately, reducing disruption for UK customers with pre-existing agreements. Notably, this regime did not extend to new investment and insurance distribution, home finance intermediation, or debt management activities — firms in those categories needed separate UK authorization from the start.
Regulatory divergence began in earnest. Since full EU rules no longer applied automatically, the UK gained the ability to diverge from EU financial regulation — in areas like transaction reporting requirements, EMIR (derivatives reporting) and SFTR (securities financing transparency) obligations, short-selling rules, and securitization regulation. In practice, divergence has been gradual rather than dramatic, with the UK broadly maintaining EU-equivalent standards in most areas while making targeted UK-specific adjustments.
The Biggest Regulatory Development Since: Consumer Duty
The single most significant UK financial regulation change since the original Brexit transition isn’t really a Brexit story at all — it’s the FCA’s Consumer Duty, which took effect in July 2023. This set a materially higher standard for how financial firms must treat retail customers, requiring firms to demonstrably act to deliver good outcomes for customers (not merely avoid harming them), covering product design, pricing and value, consumer understanding, and consumer support. It represents the most substantial shift in UK retail financial conduct regulation in years, and any current discussion of UK finance regulation that omits it is missing the most relevant recent development.
Enforcement: A Real, Verifiable Example
Rather than citing an unsourced aggregate fines figure, here’s one concrete, well-documented case: in December 2021, the FCA secured its first-ever criminal conviction of a bank under UK money laundering regulations, fining NatWest £264.8 million for anti-money-laundering failures tied to a customer that deposited roughly £365 million in cash over several years, including large amounts in bin bags. This case is widely cited as a signal of the FCA’s willingness to pursue criminal enforcement post-Brexit, not just civil penalties.
Crypto and Fintech: Genuinely Tightened Oversight
Cryptoasset businesses operating in the UK are now required to register with the FCA under UK Money Laundering Regulations, with FCA approval required before they can legally offer services to UK customers — a meaningfully stricter bar than existed before. Separately, the FCA introduced a ban on the marketing of crypto derivatives to retail consumers and has progressively tightened financial promotion rules for crypto firms more broadly, requiring clearer risk warnings and restricting how crypto products can be advertised. (A widely circulated claim that “90% of crypto withdrawal transactions were declined” during this period has no verifiable source behind it and should be treated as unsubstantiated rather than repeated as fact.)
Customer Authentication and Fraud Prevention
Strong Customer Authentication (SCA) requirements, rolled out under evolving UK payment services rules, require additional identity verification steps for online payments above certain thresholds — a direct response to rising online payment fraud. This sits alongside broader FCA efforts to flag unauthorized or scam financial firms more visibly to consumers, including an expanded public warnings list.
What This Means for Businesses and Consumers Today
For financial firms, the practical reality years into this transition is that UK and EU regulatory regimes, once identical by default, now require separate compliance tracking — a genuine added cost and complexity for firms operating across both markets. For UK consumers, Consumer Duty represents the most consequential recent change: a legal requirement that financial firms actively demonstrate good customer outcomes, not just technical rule compliance. For crypto users specifically, the registration requirement and advertising restrictions mean fewer unregistered platforms can legally market directly to UK customers, though enforcement against offshore platforms remains an ongoing challenge.
The Bottom Line
The UK’s post-Brexit financial regulatory landscape is less a single dramatic break and more an ongoing, gradual divergence — real firm relocations and job losses happened and are well-documented by New Financial’s research, but London didn’t collapse as a financial center the way some early coverage implied. The more consequential recent development for most people interacting with UK financial services isn’t a Brexit rule at all — it’s Consumer Duty, which fundamentally raised the bar for how firms must treat their customers.
Frequently Asked Questions
Did financial firms actually leave London after Brexit?
Yes, to a documented degree — New Financial’s research found over 440 firms relocated at least part of their operations, with roughly £900 billion to £1 trillion in assets and about 7,400 jobs moved to EU financial centers, primarily Dublin, Paris, Frankfurt, and Luxembourg.
What is Consumer Duty and why does it matter?
Consumer Duty is an FCA rule that took effect in July 2023, requiring UK financial firms to actively demonstrate good outcomes for retail customers across product design, pricing, communication, and support — a significantly higher bar than simply avoiding customer harm. It’s the most significant UK financial conduct regulation change in recent years.
Do crypto businesses need UK regulatory approval now?
Yes — cryptoasset firms must register with the FCA under UK Money Laundering Regulations and gain approval before legally offering services to UK customers. The FCA has also banned marketing crypto derivatives to retail consumers and tightened financial promotion rules for crypto products generally.
Is London still a major global financial center after Brexit?
Yes. While specific metrics like share-trading volume saw a notable shift in early 2021 (Amsterdam briefly overtook London), London has remained a major global financial hub in the years since — the post-Brexit story is one of real but partial relocation and regulatory divergence, not a wholesale collapse of London’s financial sector.