Buying a first home brings several decisions together: how much you can comfortably spend, which loan makes sense, what condition the property is in, and whether the location works for everyday life. Those decisions affect one another. A smaller down payment may preserve savings while changing your monthly costs. A cheaper house may need repairs that your available cash cannot cover.
For a first-time home buyer in Arkansas, the best starting point is a complete plan rather than a promise of easy approval. You do not have to eliminate every uncertainty before viewing a property. You do need to know which questions remain unanswered, who can answer them, and when a contract or payment will make your decisions harder to reverse.
This guide explains the checks to make before applying, offering, inspecting and closing. It provides general information rather than an individual lending assessment or a review of your purchase contract.
Build a budget as a first-time home buyer in Arkansas
Begin with the payment your household can sustain, not the largest loan someone might approve. Review ordinary spending, irregular bills and savings goals. Include the expenses that would continue after you become a homeowner, such as transport, childcare, insurance and existing debt payments.
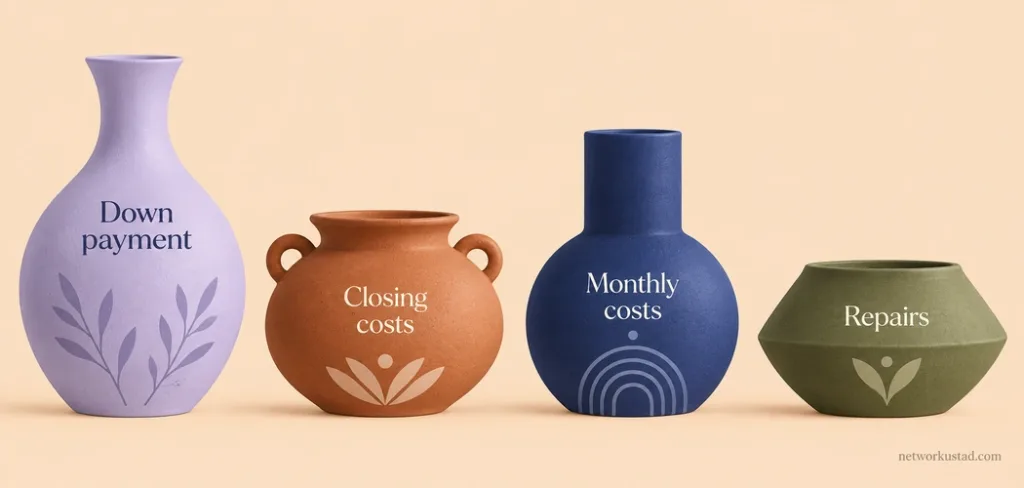
Then separate buying costs from ownership costs. Buying may involve a down payment, inspection charges, closing costs, moving expenses and cash needed for immediate work. Ownership adds ongoing mortgage payments, applicable taxes, insurance, utilities, maintenance and any association charges. The exact combination depends on the property and financing.
An approval figure does not make all of those costs comfortable. If the budget works only when nothing breaks and every month goes exactly as planned, reconsider the price range or timing. Preserve a realistic cash buffer rather than using every available dollar to complete the purchase.
Put uncertain expenses in writing
Create a simple list with three columns: expense, estimated amount and source. Mark figures that still need confirmation. An insurance estimate for the actual address is more useful than a number borrowed from another household. A utility bill from a different building may tell you little about the home you are considering.
As a first-time home buyer in Arkansas, ask your lender which expenses appear in the mortgage payment and which you must pay separately. Escrow arrangements do not mean every ownership expense is included. Association fees, maintenance and some insurance needs can require separate planning.
Compare mortgage offers beyond the interest rate
The lowest advertised interest rate is not automatically the best overall offer. A rate can come with upfront charges, a different loan term or conditions that change its value to you. Compare offers for the same kind of loan and similar assumptions wherever possible.
The Consumer Financial Protection Bureau explains how to compare Loan Estimates. Use the written estimates to examine the rate, principal-and-interest payment, mortgage insurance, lender charges, credits and cash needed at closing. Ask about anything that differs unexpectedly.
A first-time home buyer in Arkansas should also understand whether the rate is locked, when a lock expires and what happens if closing is delayed. For a loan with payments that may change, ask how and when they can change. Do not compare only the first payment if later obligations could be different.
Ask questions until you can explain the offer in ordinary language. What are you paying upfront? What is borrowed? Which costs are estimates? Which terms can change? A clear answer is more valuable than pressure to move quickly before you understand the documents.
Understand credit and debt without assuming automatic rejection
Existing debt does not, by itself, mean a mortgage application will fail. Lenders consider repayment capacity and other eligibility factors. Your monthly debt obligations relative to income are part of that picture, and different lenders and products may use different requirements.
Review your credit information early enough to investigate errors. Keep evidence of corrections and provide accurate information about income, assets and obligations. If you are self-employed, have variable earnings or expect a job change, discuss the documentation implications before relying on an informal estimate.
Avoid making major financial changes during the process without asking how they could affect the application. New borrowing, unexplained transfers or a change in employment can create additional questions. This is not a reason to conceal anything; it is a reason to communicate promptly and keep records.
For a first-time home buyer in Arkansas, the useful question is not simply whether a score is good. Ask which requirement applies to the specific product, what remains to be verified and whether any proposed change would improve your position without exhausting funds you need for closing or emergencies.
Investigate Arkansas assistance through official channels
The Arkansas Development Finance Authority, or ADFA, offers homeownership programmes through participating lenders. Its options include StartSmart and Move-Up, with down payment assistance available to qualifying borrowers using eligible first mortgages. Programme eligibility should be checked against current requirements rather than an old article or a social media promise.
Start with ADFA’s homeownership information. Ask a participating lender which programme could apply to your household, the property and the proposed mortgage. Income, property, credit and occupancy conditions can matter, and eligibility for one product does not establish eligibility for every other form of assistance.
A first-time home buyer in Arkansas should be particularly careful with the word assistance. ADFA describes its Down Payment Assistance programme as a second mortgage with repayment terms. Do not assume assistance is a grant or that accepting it eliminates other costs. Request the terms in writing, including payment obligations and what happens if you sell, refinance or stop occupying the property.
Also ask whether education is required for the specific programme you are considering, who may provide it, and when it must be completed. Confirm the current process before paying a provider. Avoid relying on a universal checklist assembled from rules for several different programmes.
Check the exact property and location
A neighbourhood description cannot replace checking the address where you would live. Test the commute at a relevant time. Identify grocery shopping, essential appointments and the services your household uses most. Consider access during ordinary working days, not only a quiet weekend viewing.
If schools matter, verify current assignment and enrolment arrangements with the relevant district. If you work from home, confirm internet service at the specific address. A broad coverage map or a nearby neighbour’s service does not necessarily settle installation options, speed or availability for your property.
A first-time home buyer in Arkansas should distinguish a mailing address from jurisdiction and service boundaries. Ask which local authority, utilities and service providers apply. Read any association documents that affect use, charges or maintenance rather than assuming every house on the same street has identical obligations.
Revisit the area if practical. Noise, parking and traffic can look different at another hour. Write down observations and questions while they are fresh, then verify consequential details through an appropriate source instead of turning one visit into a conclusion about the whole neighbourhood.
Arrange an inspection with clear expectations
An inspection is intended to provide information about the home’s condition within an agreed scope. It is not a promise that every hidden defect will be found or that no major repair will become necessary. Ask what will be inspected, what is excluded, how inaccessible areas are handled and what report you will receive.
Arkansas has registration requirements for people performing home inspections for a fee, subject to applicable exemptions. Verify the inspector’s current registration through the relevant state authority and ask about experience with the kind of property you are buying. Request a sample report and read the agreement before booking.
An appraisal serves a different purpose: estimating value for the lending process. Do not treat an acceptable appraisal as a substitute for understanding condition. Lender-required property checks also do not remove the need to understand what your own inspection covers.
For a first-time home buyer in Arkansas, attending the inspection when possible can make the report easier to interpret. Ask the inspector to distinguish observed conditions from matters needing specialist evaluation. A recommendation for further investigation is an unanswered question to resolve, not an automatic verdict that a house must be bought or rejected.
Follow up before the relevant deadline
A report may identify urgent safety concerns, maintenance items and uncertainties. Separate those categories and obtain appropriate follow-up advice or estimates. Do not convert every observation into an imagined repair bill, and do not dismiss a serious issue because the rest of the home looks attractive.
What you can request from the seller, and whether you can withdraw without a financial consequence, depends on the contract and circumstances. Have the relevant professional explain your deadlines and options. An inspection does not automatically create a cancellation right that was never included in the agreement.
Ask about water, drainage, flood exposure and insurance
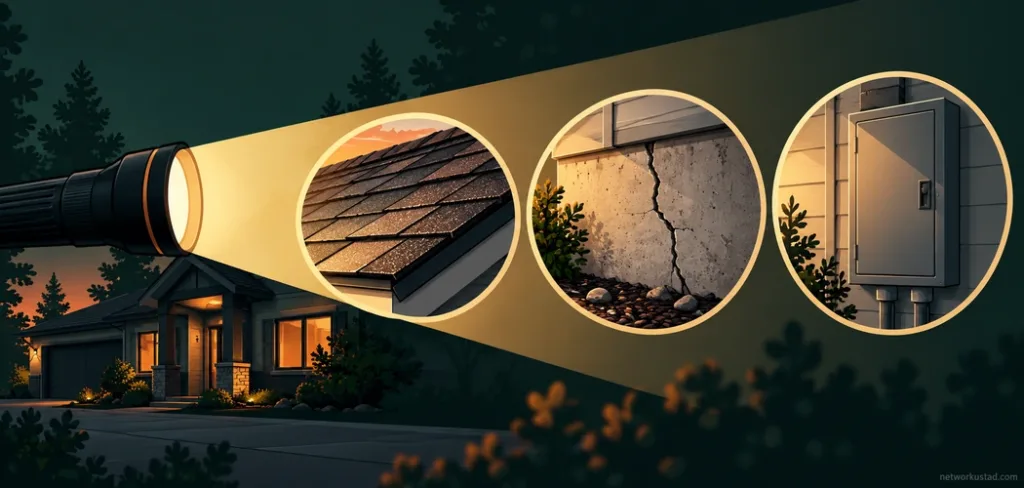
Look beyond fresh finishes when considering how the property manages water. Ask about known leaks, drainage concerns, previous water intrusion and repairs. Follow up on visible staining or a report’s recommendation rather than assuming new paint explains the condition underneath.
Check flood-related information for the actual property through official mapping and appropriate professional advice. A general statement that a neighbourhood is safe from flooding is not enough. Ask your lender and insurer about requirements, available coverage, exclusions and costs before the relevant purchase deadlines.
A first-time home buyer in Arkansas should obtain an insurance quote early enough for it to influence the budget. Discuss the building’s condition, roof information and other details the insurer requests accurately. Do not assume a quote remains valid if important property information changes.
Where a home uses a private well, septic system or other equipment outside standard utility arrangements, ask which separate evaluations and records are appropriate. A general home inspection agreement may not include every system or test you need. Establish responsibility and timing before closing becomes imminent.
Read the offer as a set of commitments
An offer is more than the purchase price. It can address deposit handling, financing, inspections, closing dates, possession and other conditions. Before signing, understand what you must do, by when, and what happens if a requirement cannot be met.
Do not assume a verbal reassurance changes the written agreement. Ask for important matters to be documented appropriately. If a repair, appliance or other item is part of your understanding, make sure the relevant documents reflect it in a form your adviser considers suitable.
A first-time home buyer in Arkansas should ask for an explanation of earnest money arrangements and any conditions affecting its return. Avoid treating every deposit as automatically refundable. The answer depends on the agreement and what occurs during the transaction.
For a consequential legal question, seek advice from an appropriately qualified Arkansas professional. A general article cannot determine the effect of a clause in your contract. Asking before signing usually leaves more room to make an informed decision than asking after a deadline has passed.
Keep closing documents and payment instructions under control
As closing approaches, review the documents supplied for your transaction and compare important figures with earlier estimates. Ask your lender or closing professional to explain material changes. Do not sign simply because several people are waiting or because a confusing charge seems small relative to the house price.
Confirm how much money is needed, the accepted payment method and the deadline through a trusted contact. Treat unexpected changes in transfer instructions as something to verify independently. Use contact details you already established rather than relying on a new message’s phone number or link.
Keep copies of signed documents, inspection findings and agreed repairs. Arrange a final walkthrough as appropriate to the transaction and confirm the agreed condition and possession arrangements. The walkthrough serves a different purpose from the earlier inspection; neither should be treated as a guarantee against every future problem.
For a first-time home buyer in Arkansas, a calm closing is partly the result of work done earlier. Accurate records, clear questions and resolved uncertainties reduce the chance that a preventable issue becomes an urgent last-minute decision.
Plan for the first months of ownership
Completion does not end the budget. Keep funds available for moving, initial maintenance and ordinary bills arriving on a different schedule. Learn where essential controls and shutoffs are located, and ask qualified professionals about anything unfamiliar rather than experimenting with potentially dangerous systems.
Make a maintenance list from the inspection and other relevant records. Prioritise safety concerns and time-sensitive work, then schedule less urgent tasks realistically. Keep warranties, service details and receipts together so you can distinguish completed work from items still awaiting attention.
Do not feel obliged to renovate everything immediately. Living in the property may help you understand which changes would actually improve daily life. Spend deliberately, especially while you are learning the home’s operating costs and settling into a new payment routine.
A final checklist before you commit
Before moving forward, confirm that you can answer these questions:
- Can the household afford complete ownership costs while retaining a practical reserve?
- Have comparable written loan offers been reviewed beyond the headline rate?
- Are assistance eligibility and repayment terms understood, if assistance is involved?
- Have inspection findings and relevant specialist questions been addressed?
- Are insurance, service availability and property-specific obligations checked?
- Do you understand the contract’s deadlines, deposit terms and closing arrangements?
A first-time home buyer in Arkansas does not need perfect foresight. A sound process identifies the important unknowns, checks them using reliable information and avoids treating approval, an attractive listing or a reassuring conversation as proof that every part of the purchase is suitable.
This article provides general homebuying information and does not constitute personalised financial, mortgage, legal, insurance or property advice. Loan eligibility, assistance programmes, rates and requirements may change. Confirm current terms with the relevant authority and lender. Obtain qualified advice on your contract and property, and verify inspection scope and professional credentials. No loan approval, assistance award or defect-free property is guaranteed. Images are conceptual illustrations, not representations of available properties or actual cost proportions.